Your BTO is paid in stages, not all at once
Getting your BTO is a big moment, and the price on the flat is only part of the picture. The money goes out in stages over several years, some of it has to be cash, and a few of the biggest costs aren't on HDB's bill at all. Knowing when each payment falls due lets you plan your cash and CPF early, instead of scrambling when the letter arrives. Key takeaways
- You pay at three main points: when you book the flat, when you sign the Agreement for Lease, and when you collect your keys.
- The total downpayment is 25% of the purchase price, whether you take an HDB loan or a bank loan.
- With a bank loan, 5% of the price must be paid in cash. With an HDB loan, the downpayment can come from CPF, cash or both.
- The option fee is cash only, and renovation, furniture and moving costs are usually paid in cash too.
- Plan these costs early. Being able to borrow more doesn't mean you should borrow more. Loanify is a loan matching service, not a lender. Approval, contracts and disbursement are handled by the licensed moneylender you accept an offer from. Loanify is free for borrowers.
Your BTO cash timeline at a glance
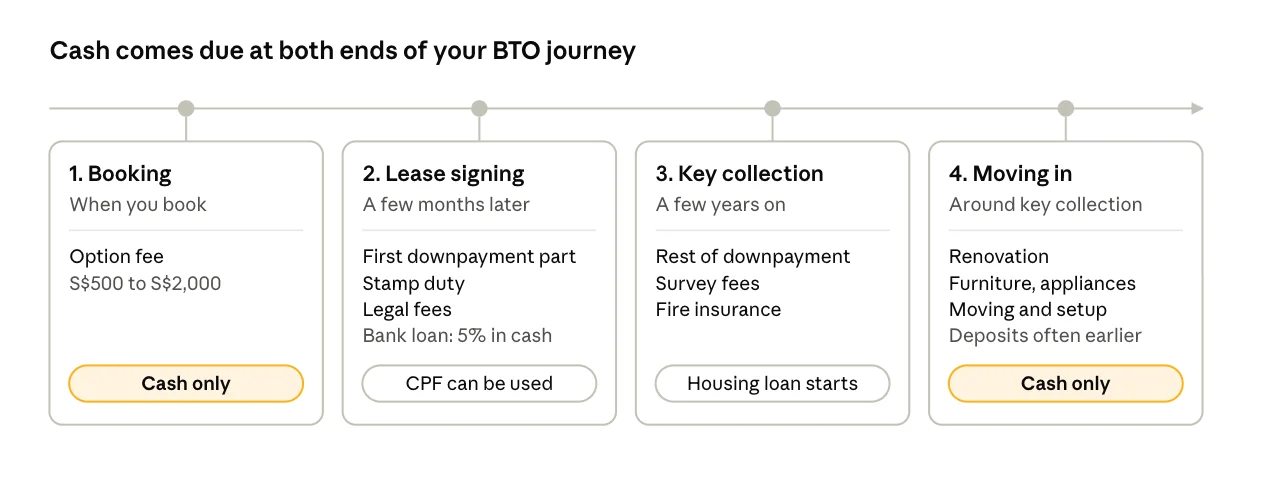 The middle stages can largely be covered by CPF and your housing loan. The start and the end are where cash matters most.
Stage by stage: what you pay, and how
1. Booking your flat
When you book, you pay an option fee in cash. CPF can't be used for it. The option fee counts toward your downpayment, so it isn't an extra cost, but it does need to be in your bank account on the day.
| Flat type | Option fee |
| 4-room and bigger | S\$2,000 |
| 3-room | S\$1,000 |
| 2-room Flexi | S\$500 |
2. Signing the Agreement for Lease
A few months after booking, you sign the Agreement for Lease and pay the first part of your downpayment. [CONFIRM: exact first-instalment % for HDB loan vs bank loan, and the Staggered Downpayment Scheme split, against HDB's current page.] At this stage you'll also pay:
- Stamp duty on the Agreement for Lease, at progressive rates starting from 1% on the first S$180,000.
- Legal fees for the conveyancing. Both can be paid with your CPF Ordinary Account savings. If you're taking a bank loan, remember the cash rule. Of the 25% downpayment, 5% of the purchase price must be paid in cash. On a S$500,000 flat, that's S$25,000 in cash. With an HDB loan, the full 25% can come from CPF, cash or a mix. If you're eligible, HDB's Staggered Downpayment Scheme lets you pay a smaller portion now and more at key collection. It doesn't reduce the total, it only changes when each portion is due.
3. Collecting your keys
When the flat is ready, usually a few years later, you pay the rest of your downpayment and your housing loan starts. Smaller fees also come due around this time, including:
- Survey fees, from S$163.50 to S$408.75 depending on flat type
- Fire insurance, which is compulsory for HDB flats with an HDB loan
- Home Protection Scheme cover if you use CPF for your monthly instalments
- Service & Conservancy Charges, from about S$21 to S$123 a month, once you move in Figures from CPF Board, as published in 2026. HDB's rules can change, so check the latest figures on HDB's website before you book.
The costs that aren't on HDB's bill
HDB's payments are predictable. The costs around them often aren't, and most of them have to be paid in cash.
- Renovation deposits. Many contractors ask for a deposit when you sign with them, which can be before you've collected your keys. The rest is usually paid in stages as the work progresses.
- Furniture and appliances. Beds, sofas, a fridge, a washing machine and lighting add up quickly, and they're often bought within weeks of each other.
- Moving and setup. Movers, curtains, cleaning, internet installation and small fixes in the first month.
- Overlap costs. If you're renting while you wait, you may pay rent and your first loan installments at the same time for a while. None of these can be paid with CPF. Get two or three quotes for renovation early, and list your must-haves separately from your nice-to-haves. That gives you a realistic cash number to save toward.
Planning for the gap, and where a loan fits
The best plan is a cash buffer built before you ballot. Work out your cash-only costs (option fee, any cash portion of the downpayment, renovation, furniture and moving), then compare that number with your savings and when you'll have them. A few things are worth settling early:
- Your housing loan. Get an HDB Flat Eligibility (HFE) letter, or an in-principle approval if you're using a bank, so you know how much you can borrow for the flat.
- Your CPF. Check how much is in your Ordinary Account and what it can cover.
- Family help. If parents are chipping in, agree on the amount and the timing now, not the week a payment is due.
Where a personal loan can fit
A personal loan from a licensed moneylender is not a way to fund your downpayment. It can help with a short, specific gap, such as furniture or the last part of a renovation, if you know how you'll repay it. Before you borrow, ask yourself:
- Can I repay this comfortably alongside my monthly housing loan instalment?
- Is this a need, or something that can wait a few months?
- Have I checked how new debt might affect my housing loan? Lenders consider your existing commitments, so speak to your housing loan provider first if your loan isn't finalised. Being able to borrow more doesn't mean you should borrow more. Borrow only what you need, for the purpose you have. If you're unsure, talk to us. A real person from our team will listen to what you need and explain your options. If you decide to go ahead, we'll match you with a suitable licensed moneylender from our partner network.
Frequently asked questions
**How much cash do I need for a BTO?**
At minimum, the option fee (S\$500 to S\$2,000 depending on flat type). With a bank loan, you also need 5% of the purchase price in cash. On top of that, budget cash for renovation, furniture and moving, since CPF can't be used for these.**Can I use CPF for the option fee?**
No. The option fee must be paid in cash. It counts toward your downpayment.**Can I use CPF for stamp duty and legal fees?**
Yes. You can use your CPF Ordinary Account savings for both.**Is the downpayment different for an HDB loan and a bank loan?**
The total is 25% of the purchase price for both. The difference is the cash rule: with a bank loan, 5% of the price must be cash, while with an HDB loan the full 25% can come from CPF, cash or both.**Can I use a personal loan for my downpayment?**
A personal loan isn't meant to fund your downpayment. Plan your downpayment with your savings, CPF and housing loan. A personal loan may help with a short-term gap like furniture, but only if you can repay it comfortably.**Does Loanify charge me a fee?**
No. Loanify is free for borrowers. We may receive a commission from our partner lenders.Talk to a real person
Planning for your new home and not sure how to bridge a short gap? Apply once with Singpass and a real person from our team will reach out to talk it through, with no obligation to accept any offer. It's free for borrowers. Matched, not sold. Apply now and our team will reach out within 24 hours → Borrow only what you need and can comfortably repay. Compare the full cost of a loan, including fees and total interest, before accepting any offer. *Loanify is a loan matching service, not a lender. Loanify does not guarantee approval. Approval, loan contracts, interest rates, fees and disbursement are determined and handled by the licensed moneylender you accept an offer from. * *This article is general information and should not be treated as personalised financial advice. HDB and CPF figures are correct as published by CPF Board in 2026 and may change. Questions? Email contact@loanify.sg or call +65 6041 4104. Loanify Pte. Ltd. *